Last Updated: October 26, 2026
Quick Summary
The best tips for first time car buyers are to set a realistic budget, get preapproved for financing, and compare loan offers on APR and total repaid before signing. A prepared car buyer also researches total cost of ownership, gets an insurance quote and arranges an independent inspection before committing.
- The 20/4/10 rule means 20% down, a four-year term and total costs under 10% of gross income.
- Compare at least three financing offers on the same vehicle and term before signing.
- Ask every lender in writing for the APR and the total amount you will repay.
- Get an insurance quote for the exact make, model and year before you commit.
- Negotiate the out-the-door price, never the monthly payment, and be ready to walk away.
Table of Contents
- Start With a Realistic First Car Budget and Financing Plan
- Decide Between a New Car and a Used Car
- Research Vehicle Types That Fit Your Lifestyle Needs
- Calculate the Total Cost of Ownership, Not Just the Purchase Price
- Compare Financing Options and Loan Terms Side by Side
- Plan Your Down Payment and Understand the Out-the-Door Price
- Get an Insurance Quote Before You Commit
- Use a Used Car Inspection Checklist Before You Buy
- Questions to Ask When Buying a Used Car
- How to Negotiate a Used Car Price Without the Pressure
- Know Your Credit Situation and Whether a Co-Signer Helps
- Buying From a Dealership, a Private Seller or Online
- Review the Paperwork, Contract and Warranty Before Signing
- Your Post-Purchase Checklist for the First Month of Ownership
- Book a Test Drive and Trade-In Appraisal With Variety Auto
- Frequently Asked Questions
Start With a Realistic First Car Budget and Financing Plan
The best tips for first time car buyers start in a spreadsheet, not a showroom.
Your budget has two layers. The first is the purchase budget: what you can put down plus what you can comfortably finance. The second is the ownership budget: insurance, fuel, maintenance, registration and a repair cushion.
A common approach is to total your essential monthly costs first, then decide what a vehicle can take without squeezing everything else.
The 20/4/10 Rule and What It Means for Your Monthly Payment
The 20/4/10 rule is a budgeting guideline for car financing: 20% down, a loan term no longer than four years, and total vehicle costs no more than 10% of gross monthly income. It is a starting point, not a law, but it keeps first-time buyers out of the seven-year-loan trap.
Here is how the rule breaks down in practice:
- 20% down: reduces the amount financed and keeps you from going underwater on a depreciating asset
- 4-year term: limits interest paid and keeps the loan shorter than the vehicle's useful life
- 10% of income: covers payment plus insurance, so the car does not crowd out rent or savings
If 20% down is out of reach, a smaller down payment is workable. Just shorten the term instead.
Getting Preapproved for an Auto Loan Before You Shop
Preapproval is a lender's conditional commitment to finance you up to a set amount, and it changes how you negotiate. A preapproved car buyer walks in with a number, not a hope.
Gather your identification, proof of income, proof of address and banking details before you apply. You can apply for vehicle financing through a secure online credit application and get a clearer picture of your approval.
Watch out: a preapproval is not a guarantee, and the final rate depends on the specific vehicle, term and your credit profile at signing.
Decide Between a New Car and a Used Car
For most first-time buyers, a used car is the smarter financial move.
That said, new has real advantages: full warranty coverage, the latest safety technology and no unknown history.
The honest trade-off is risk versus cost. A used car carries some uncertainty, which is why the inspection steps later in this guide matter so much. A new car carries certainty, at a price.
Research Vehicle Types That Fit Your Lifestyle Needs
A car that fits your commute can be wrong for your weekends.
Vehicle type drives most of your ownership costs. A compact hatchback uses less fuel and costs less to insure than a mid-size SUV, but it carries less.
If fuel economy and maneuverability top your list, browsing used hatchbacks for sale in Vancouver shows you real listings with current prices, mileage and features to compare against your shortlist.
Once you have two or three candidates, compare them side by side on reliability history, safety ratings and insurance cost. A vehicle that saves on the sticker but costs more to insure and repair is not a saving.
Calculate the Total Cost of Ownership, Not Just the Purchase Price
The purchase price is the smallest number in the deal. Total cost of ownership is the full amount a vehicle costs you from purchase to resale, including depreciation, fuel, insurance, maintenance, repairs, registration and financing interest.
Two vehicles with the same sticker price can differ by thousands over four years. A cheaper model with poor fuel economy and expensive parts can cost more than a pricier one that holds value and sips fuel.
Build a simple ownership estimate before you commit:
- Estimate annual kilometres driven
- Divide by the vehicle's combined fuel consumption to get annual fuel cost
- Add insurance premiums for that specific model
- Add scheduled maintenance for the term you will own it
- Add a repair cushion for an older vehicle
- Add registration and any local fees
- Subtract the estimated resale value at the end of your term
Depreciation, Fuel Economy, Maintenance and Repair Costs
Depreciation is the largest single cost of ownership for most vehicles, and it is invisible because you never write a cheque for it. A vehicle that loses value quickly costs you more even if it never breaks down.
Fuel economy compounds over time. A small difference in litres per 100 kilometres adds up across a year of commuting. Maintenance and repair costs vary by model and by how well the previous owner cared for it, which is why a documented service history is worth paying attention to.
Compare Financing Options and Loan Terms Side by Side
Financing is where the same vehicle becomes two very different purchases. A car buyer should compare at least three offers on the same vehicle and the same term before signing anything. The variables that matter are the interest rate, the APR, the term length and any fees rolled into the loan.
| Loan Feature | Shorter Term | Longer Term |
|---|---|---|
| Monthly payment | Higher | Lower |
| Total interest paid | Lower | Higher |
| Risk of negative equity | Lower | Higher |
| Fit for first-time budget | Tight but disciplined | Easier cash flow, costlier overall |
Compare the APR, not just the rate. The APR includes fees, so it reflects the true annual cost of borrowing. A lower rate with high fees can cost more than a slightly higher rate with none.
Ask each lender for the total amount you will repay over the life of the loan. That single number makes offers comparable in a way monthly payments never do.
A Worked Example: Three Offers on the Same Vehicle
Suppose you are financing $25,000 after your down payment on the same used vehicle. Three lenders quote different structures. Here is how they compare on total cost, using simple amortization math:
| Offer | Rate | Term | Monthly Payment (approx.) | Total Interest (approx.) | Total Repaid (approx.) |
|---|---|---|---|---|---|
| A | 7.9% | 48 months | $609 | $4,232 | $29,232 |
| B | 8.4% | 60 months | $512 | $5,720 | $30,720 |
| C | 6.9% | 48 months, $500 fee | $598 | $3,704 + $500 fee | $29,204 |
Offer B has the lowest monthly payment but costs about $1,500 more in interest than Offer A. Offer C has the lowest rate but the fee narrows the gap; its APR, not its rate, is the number to compare.
These figures are illustrative and rounded. Your actual numbers depend on the lender, your credit profile and the vehicle. Ask each lender for the APR and the total repaid, then compare those two numbers side by side.
What APR Includes and Why It Matters
The APR folds the interest rate and most lender fees into one annualized percentage, so it reflects the true cost of borrowing. A 6.9% rate with a $500 origination fee can produce an APR higher than a 7.5% rate with no fee.
Watch for fees that may sit outside the APR, such as documentation fees charged by the dealer rather than the lender. Ask for the full itemized cost of credit in writing.
Preapproval, Dealer Financing and Your Leverage
A preapproval from a bank or credit union gives you a benchmark rate and a maximum amount before you shop.
A practical approach is to get preapproved first, then let the dealer try to beat your preapproval on the same vehicle and term. If the dealer's offer is better on APR and total repaid, take it. If not, use your preapproval.
How Term Length Changes Your Risk
A longer term lowers the payment but keeps you in negative equity longer, because the vehicle depreciates faster than you pay down the loan. If you need to sell or the vehicle is written off, you may owe more than it is worth. A shorter term with a slightly higher payment usually costs less overall and protects your equity position.
Plan Your Down Payment and Understand the Out-the-Door Price
The out-the-door price is the final amount you pay, including the vehicle price, taxes, registration, documentation fees and any add-ons.
Ask for the out-the-door figure in writing before you discuss monthly payments.
Your down payment reduces both the amount financed and the interest you pay over the term.
Watch out: add-ons like fabric protection, extended warranties and tire packages inflate the out-the-door price.
Get an Insurance Quote Before You Commit
Insurance quotes change the affordability of a vehicle, and first-time buyers often skip this step until after purchase. Get a quote for the specific make, model and year before you commit.
In Canada, auto insurance is regulated provincially, so requirements and rating factors differ by province.
A first-time buyer with no insurance history may pay more at the start. Asking about usage-based or telematics programs can offset that.
Use a Used Car Inspection Checklist Before You Buy
A used car inspection checklist is a structured set of checks a buyer performs before purchase to confirm a vehicle's condition, history and roadworthiness. Working through one systematically catches problems that a short test drive hides.
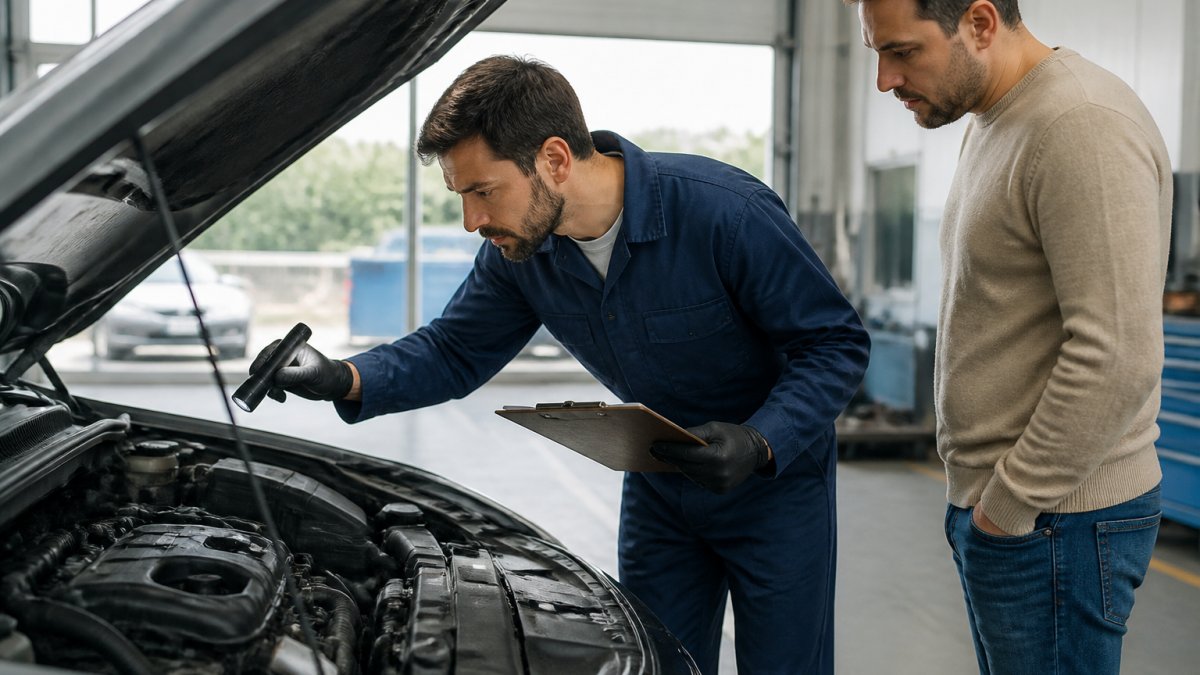 Mechanic inspecting a used sedan engine with a car buyer watching nearby
Start with the paperwork, then the metal:
- Verify the VIN on the vehicle matches the ownership documents
- Pull a vehicle history report for accidents, liens and odometer rollback
- Check for rust at wheel arches, rocker panels and the frame
For a fuller walkthrough, our guide on 20 things to check before buying a used car covers VIN and history checks through to the test drive and paperwork.
What a Pre-Purchase Inspection by a Mechanic Should Cover
A pre-purchase inspection is an independent mechanical assessment of a used vehicle performed before purchase, typically on a hoist, covering the engine, transmission, brakes, suspension, steering, exhaust and frame.
The inspection should include a compression or diagnostic scan, a brake measurement, a suspension and steering check, a look for fluid leaks and frame damage, and a road test. Ask for the written report.
If you are weighing the cost against a tight budget, our article on whether a pre-purchase inspection is worth it on a budget used car breaks down what you get for the fee and when to skip it.
Questions to Ask When Buying a Used Car
The right questions to ask when buying a used car separate a confident buyer from an easy mark. Ask them early, ask them in writing where possible, and listen for hesitation.
- Why is the vehicle being sold?
- How many owners has it had, and do you have the full service history?
- Has it been in any accidents, and was any damage repaired?
- Is there any outstanding lien or loan against it?
- What is the exact out-the-door price, itemized?
- What warranty, if any, comes with the vehicle?
- Can I take it for an independent inspection?
- Are there any known issues I should expect?
A seller who resists the inspection question is telling you something. Treat that as an answer.
How to Negotiate a Used Car Price Without the Pressure
Negotiating a used car price is a structured conversation, not a contest. The buyer with a preapproval, a researched market value and the willingness to walk away holds the use.
Research comparable listings for the same model, year and mileage before you negotiate. Know the out-the-door price you want and the maximum you will pay. Then make a single, reasonable offer backed by your research.
Here is how we would approach it:
- Let the seller make the first price statement
- Present your comparable listings as the basis for your offer
- Negotiate on the out-the-door price, never the monthly payment
- Ask for the itemized breakdown of every fee
- Be ready to walk away if the numbers do not work
Negotiate the Out-the-Door Price, Not the Monthly Payment
The out-the-door price is the only number that matters. It includes the vehicle price, taxes, registration, documentation fees and any add-ons.
Ask for the out-the-door figure in writing before you discuss financing. Then work backward: out-the-door price minus your down payment equals the amount financed.
A simple script sets the frame early:
"Before we talk payment, can you give me the out-the-door price in writing, itemized by vehicle price, taxes, registration, documentation fee and any add-ons?"
If the seller quotes a payment instead, repeat the request. A seller who will not itemize is telling you something.
Fee-by-Fee: What to Question and What to Accept
Not every fee is negotiable, and not every fee is legitimate. Ask what each line covers and whether it is required by law or set by the dealer.
- Documentation fee: A dealer charge for paperwork. It is often negotiable or can be reduced; ask what it covers.
- Registration and title fees: Usually government-set and not negotiable. Confirm the amount matches your province's schedule.
- Taxes: Set by law. Confirm the rate and the taxable amount.
Scripts for Handling Dealer Add-Ons and Fees
Use these scripts when the add-on conversation starts:
"Thanks, but I have my financing arranged and I am not adding protection packages today. Can you show me the out-the-door price without them?"
"I see a documentation fee here. Can you explain exactly what it covers and whether it is negotiable?"
"I would like to take the vehicle for an independent inspection before we finalize.
"Can you itemize every add-on with its price and tell me which ones are optional?
"I am comparing this out-the-door price against two other listings. If you can match this number, I am ready to move forward today."
Polite, firm and specific. You are not being difficult; you are being a prepared car buyer.
Add-On Decision Rules: What to Keep and What to Skip
Add-ons inflate the out-the-door price and are often high-margin for the seller. Decide before you sit down using these rules:
- Extended warranty: Worth considering on a vehicle with a complex powertrain and a short remaining factory warranty. Read the exclusions and the claim process. Skip it if the vehicle already has strong factory coverage.
- Fabric or paint protection: Usually low value relative to cost. Skip unless the price is trivial and you specifically want it.
- Tire and rim package: Can pay off in pothole-heavy regions, but check the deductible and exclusions. Often skippable.
Ask for the price of each add-on separately and in writing. A bundled price hides the cost of the items you do not want.
When to Walk Away
Walking away is a negotiating tool, not a failure. Walk if the out-the-door price exceeds your researched maximum, if the seller refuses an independent inspection, if the fee schedule is incomplete, or if the pressure tactics start. There is always another vehicle. The buyer who can walk away is the buyer who gets the fair price.
Know Your Credit Situation and Whether a Co-Signer Helps
Your credit profile determines your interest rate and your approval odds. Pull your credit report before you shop, check for errors and understand where you stand.
A co-signer is someone who agrees to share legal responsibility for the loan, and their credit history can improve your approval odds and rate.
Rough credit from past issues does not mean you cannot get approved.
Buying From a Dealership, a Private Seller or Online
Each buying channel carries different risk and different protection. A dealership typically provides reconditioned inventory, financing support and some form of warranty. A private seller often offers a lower price but no warranty and more paperwork risk.
| Channel | Main Advantage | Main Risk | Best For |
|---|---|---|---|
| Dealership | Financing and warranty support | Higher list price | First-time buyers who want support |
| Private seller | Lower price | No warranty, lien risk | Confident buyers with inspection access |
| Online | Convenience and delivery | Limited physical inspection | Buyers who know exactly what they want |
At Variety Auto, our full inventory is online, our finance application is online, and you can still inspect and test drive before you commit.
Review the Paperwork, Contract and Warranty Before Signing
The contract is the deal. Everything discussed before signing means nothing if it is not written into the agreement. Read the entire document, including the fine print on financing terms, add-ons and warranty coverage.
Confirm these items before you sign:
- The out-the-door price matches what you agreed
- The interest rate and APR match your preapproval
- The term length is what you intended
In Canada, vehicle sales contracts fall under provincial consumer protection rules, and many provinces require specific disclosures. If a term is unclear, ask for it in writing before you sign.
Your Post-Purchase Checklist for the First Month of Ownership
The first month sets up the next several years. A new owner who handles registration, insurance and a baseline service right away avoids surprises later.
- Transfer the registration and plates within your province's required timeframe
- Confirm insurance is active before you drive off
- Book a baseline service or oil change to establish a maintenance record
A repair cushion in your budget for the first year is wise. Even a well-inspected used vehicle can need a battery, brakes or tires sooner than expected.
Book a Test Drive and Trade-In Appraisal With Variety Auto
A test drive is the final filter. No checklist or review replaces sitting in the vehicle, adjusting the seat, and driving the roads you actually drive.
If you have a current vehicle, a trade-in appraisal turns it into part of your down payment.
Start with our online inventory, submit a finance application when you are ready, and book a test drive with the vehicle you want to see.
Frequently Asked Questions
What is the 20/4/10 rule for buying a car?
The 20/4/10 rule is a budgeting guideline: put down at least 20 percent of the purchase price, finance for no more than four years, and keep total vehicle costs (loan payment plus insurance) under 10 percent of your gross monthly income. It is a starting point, not a hard rule. If a shorter loan term pushes the monthly payment beyond your comfort zone, a less expensive vehicle usually beats stretching the term to seven or eight years, which raises the interest you pay and keeps you upside down longer.
How much should a first-time car buyer spend on a car?
A common approach is to keep the total monthly cost of the car, including the auto loan payment and insurance, at or below about 10 to 15 percent of your take-home pay. Work backward from that number to find your purchase price, then add taxes and fees to get the out-the-door price. Leave room in your budget for fuel, maintenance and registration. A first car budget and financing plan should account for all of these, not just the sticker price.
Should a first-time car buyer buy new or used?
Used cars usually make more sense for a first purchase. Depreciation hits hardest in the first few years, so a vehicle that is two to four years old has already absorbed the steepest drop in value while still offering modern safety features and reliability. A used car also lowers your insurance and registration costs in most cases. The trade-off is that you need a proper used car inspection checklist and a vehicle history report to confirm condition before you commit.
What should you check before buying a used car?
Run a vehicle history report for accidents, liens and odometer rollback. Have an independent mechanic perform a pre-purchase inspection covering the engine, transmission, brakes, suspension, tires and frame. Check for rust, mismatched paint and warning lights. Confirm the mileage matches the service records, verify the ownership paperwork, and ask whether any warranty remains. Skipping the inspection to save an hour is the most common and most expensive mistake a first-time buyer makes.
How can a first-time car buyer negotiate the price?
Get preapproved for financing first so you negotiate as a cash-equivalent buyer. Research the fair market value of the specific model, trim and mileage, then make a reasonable opening offer below your target. Negotiate the out-the-door price, not the monthly payment, so fees and add-ons cannot hide in a longer loan term. Ask for add-ons to be itemized and decline anything you did not plan to buy. Walking away from a deal that does not fit your budget is always an option.
What credit score is needed to finance a first car?
There is no single cutoff, but a score in the mid-600s or higher generally opens up standard auto loan rates. Below that, lenders may still approve you at a higher interest rate or ask for a co-signer. A co-signer with strong credit can lower your rate and improve approval odds, though they share legal responsibility for the loan. Applying for preapproval before you shop lets you see your real rate and terms without a hard pull on your credit at every dealership.
Buying your first car should feel like a decision you made, not one that was made for you. Variety Auto gives you the tools to do it your way: a curated inventory you can browse online, a secure finance application with a simplified approval process, and trade-in appraisals that put a real number on your current vehicle. Get started with Variety Auto and shop with a clear budget, a preapproval and a plan.
